Stablecoins have become an essential part of the crypto market, letting traders and investors hold digital dollars without the price swings of assets like Bitcoin and Ethereum. Their usefulness depends on one promise: staying close to $1. When that value slips, even by a few cents, the consequences can be serious, and this loss of stability is known as stablecoin depegging.
Key takeaways
- Fully backed stablecoins can experience depegging because sufficient reserves do not guarantee immediate liquidity or uninterrupted redemption.
- During the March 2023 crisis, Circle disclosed that $3.3 billion of USDC reserves were held at Silicon Valley Bank, representing approximately 8% of its reserves.
- The main risk is that banking disruptions, redemption delays and declining confidence can weaken a stablecoin’s peg even when its issuer remains solvent.
- Before holding a stablecoin, examine its reserve composition, redemption policies, banking exposure and independent reserve reports.
Definition
Stablecoin depegging is a situation in which a stablecoin’s market price moves away from its intended reference value, such as $1 for a dollar-pegged token. A depeg can be
temporary or persistent, depending on the underlying cause, market confidence and the issuer’s ability to maintain redemption.
How Stablecoins Maintain a Dollar Peg Before Depegging Occurs
A fiat-backed stablecoin generally maintains its value through a combination of reserve assets, issuance and redemption mechanisms, and secondary-market trading.When an eligible customer deposits $1 with an issuer, the issuer can create one stablecoin in return. The token then circulates across exchanges, wallets and decentralized applications. When a customer returns the token for redemption, the issuer removes the corresponding token from circulation and pays out the dollar equivalent, subject to its terms and procedures. The expectation that one token can be redeemed for one dollar creates the foundation of the peg. However, primary and secondary markets serve different purposes.
Primary Market
The primary market is where eligible customers interact directly with the issuer to create or redeem stablecoins.
Secondary Market
The secondary market consists of exchanges and other trading venues where users buy and sell tokens among themselves. As a result, the market price can move away from $1 even when the issuer’s reserves are sufficient to cover the outstanding supply.
Why Full Reserves Cannot Prevent Stablecoin Depegging
Holding reserves equal to a stablecoin’s circulating supply does not guarantee that its market price will remain at $1. The problem lies in how those reserves are held and how quickly they can be accessed. Issuers typically distribute their assets across bank deposits, short-term government securities and other financial instruments rather than keeping everything in cash. This creates a liquidity challenge during periods of heavy redemption. An issuer may have enough assets to cover every token in circulation but still struggle to meet sudden withdrawal demands if a large portion of its reserves cannot be converted into cash immediately. Banking disruptions can make the situation worse by temporarily restricting access to deposited funds.
Market Access
Market access also plays an important role. While institutional participants may redeem tokens directly with issuers, ordinary holders often depend on exchanges and liquidity pools. When redemption becomes difficult or confidence weakens, selling pressure can push a stablecoin below $1 even if its reserves remain sufficient.
“Redeemability of stablecoins is equally as important”
Edward Woodford, founder and CEO of Zero hash.
Myth vs fact
A fully backed stablecoin cannot lose its dollar peg.
Reserve backing addresses the value of an issuer’s assets relative to its liabilities. It does not guarantee immediate access to cash, unrestricted redemption or stable secondary-market prices
Source: name the source and link to it.
How Solvency and Liquidity Affect Stablecoin Depegging Risk
Solvency and liquidity are two financial concepts that plays a major role in affecting the stability of stablecoins. Solvency refers to an issuer’s ability to cover its outstanding obligations with its total assets, while liquidity describes how quickly those assets can be converted into cash to meet redemption requests. Both are essential to stablecoin stability, but they address different financial risks.
| Solvency | Liquidity |
| Measures whether an issuer has sufficient assets to cover outstanding stablecoins | Measures whether an issuer can access cash to process redemptions |
| Depends on the value and quality of reserve assets | Depend on cash availability and asset convertibility |
| Can remain intact during temporary financial disruptions | Can deteriorate when withdrawals increase or banking access is restricted |
| Does not guarantee immediate redemption | Determines how quickly redemption requests can be fulfilled |
How Arbitrageurs Help Reverse Stablecoin Depegging
Arbitrageurs are among the most important participants in maintaining stablecoin prices.
When a stablecoin trades below $1, an eligible trader may purchase it at a discount and redeem it with the issuer for approximately one dollar. The difference creates an opportunity for profit while simultaneously reducing selling pressure in the secondary market.
for example
If USDC trades at $0.98, an eligible market participant could buy 100,000 USDC for $98,000 and redeem those tokens for approximately $100,000. The potential gross difference is $2,000 before fees, operational costs and other expenses.
The reverse process can occur when a stablecoin trades above its peg. An eligible participant can deposit dollars, receive newly issued tokens and sell them at a premium.
These transactions connect the primary and secondary markets. As arbitrageurs buy discounted tokens, demand increases and the market price can move closer to its intended value.
However, this mechanism depends on several conditions:
- Direct redemption must be available to eligible participants.
- The issuer must have access to sufficient liquidity.
- Banking and settlement systems must remain operational.
- Traders must be willing to absorb the risk of holding discounted tokens.
- The expected profit must exceed transaction costs and redemption delays.
When these conditions deteriorate, arbitrage becomes less effective precisely when the market needs it most.
Myth vs fact
Arbitrageurs always restore the peg.
Arbitrage depends on functioning redemption channels, sufficient liquidity and confidence that the issuer will honor its obligations.
The 2023 USDC Depeg: A Real-World Case of Stablecoin Depegging
The collapse of Silicon Valley Bank in March 2023 provided a real-world example of how traditional financial stress can affect a reserve-backed stablecoin. USDC issuer Circle disclosed that $3.3 billion of its reserves, approximately 8% of the total at the time, remained deposited at SVB when the bank entered receivership.
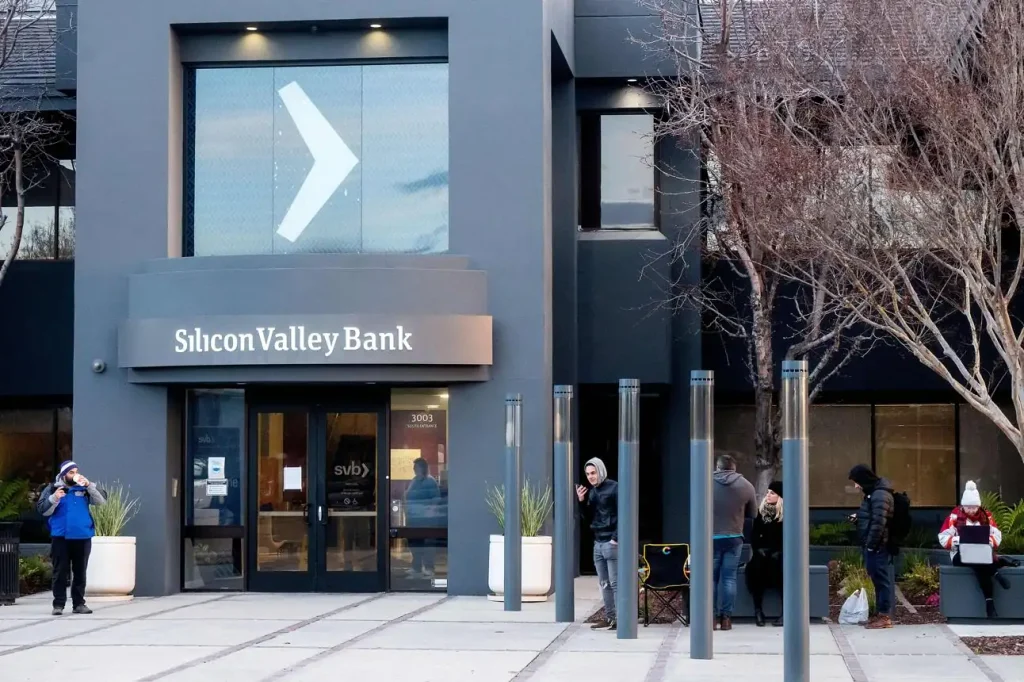
The announcement triggered concerns about whether Circle could access those funds and meet redemption requests. USDC began losing its dollar peg as holders moved to sell their tokens. The selling intensified over the weekend when Circle’s normal issuance and redemption operations were constrained by banking-system operating hours.
At its lowest point, USDC traded at approximately $0.86.
The episode was particularly revealing because the crisis did not originate from a failure of the blockchain or a direct exploit of USDC’s smart contracts. It came from the traditional banking infrastructure supporting its reserves. The disruption also affected other stablecoins.
For example
DAI, had significant exposure to USDC through MakerDAO’s Peg Stability Module, a mechanism that allowed users to exchange USDC and DAI at a predetermined rate. As USDC came under pressure, this connection transmitted stress into DAI’s market price.
Federal Reserve’s Analysis
The Federal Reserve’s subsequent analysis documented how this arrangement became a channel through which instability spread between otherwise different stablecoin systems. The situation improved after US authorities announced that all SVB depositors, including uninsured depositors, would be protected. Circle subsequently resumed normal redemption operations, and USDC returned to its dollar peg. The incident demonstrated that stablecoin stability depends not only on the assets held by an issuer but also on the institutions, counterparties and financial infrastructure surrounding those assets.
Myth vs fact
A stablecoin depeg is always evidence of insolvency.
A temporary price deviation can result from liquidity shortages, operational disruptions or market panic even when the issuer remains solvent.
When Stablecoin Depegging Becomes a Systemic Risk
The consequences of a depeg can extend far beyond the stablecoin itself.
Stablecoins are frequently used as collateral in decentralized lending protocols, liquidity pools and other financial applications. When a major stablecoin loses value, these interconnected positions can become vulnerable.
For example
a lending protocol that accepts a dollar-pegged token as collateral may calculate borrowing limits based on the assumption that the token is worth $1. If its market price falls, the value of collateral declines. Borrowers can face liquidation, while protocols may experience additional selling pressure as liquidators attempt to recover outstanding loans.
Liquidity
Liquidity pools can also become imbalanced. Traders may withdraw the more trusted asset while leaving the discounted stablecoin behind. This can deepen the discount and make it more difficult for remaining holders to exit without accepting further losses.
There is also a potential connection to traditional financial markets.
As stablecoin issuers increasingly hold government securities in their reserve portfolios, large redemption waves could force them to sell those assets. If several issuers face simultaneous pressure, concentrated selling could affect short-term funding markets and government bond liquidity.
An IMF working paper published in January 2026 examines this feedback mechanism, which includes the following
- Redemptions can deplete reserves,
- Redemptions can also force asset sales.
- It can also depress bond prices and potentially weaken an issuer’s financial position, creating further incentives to redeem.
This creates a broader question for financial regulators. A stablecoin may begin as a privately issued digital token, but as its reserves and market connections expand, its stability can become relevant to the wider financial system.
Tip
What to examine before trusting a dollar-pegged stablecoin, For example: Do not focus exclusively on the total value of reported reserves. Examine the composition of those reserves, the institutions holding them, the frequency of independent reporting, redemption eligibility and the issuer’s ability to meet large withdrawal requests.
Conclusion
The promise of a stablecoin is not simply that every token has an equivalent dollar value somewhere in reserve. Its real test is whether holders can rely on that dollar value when market conditions deteriorate. The USDC crisis demonstrated that even a reserve-backed stablecoin can experience a significant depeg when access to banking infrastructure becomes uncertain and redemption activity faces operational constraints. Arbitrage can help restore the peg, but it cannot function effectively when the channels connecting issuers, banks and markets are disrupted.
As stablecoins become more deeply integrated into digital finance, the industry will need to move beyond measuring reserves alone. Greater attention must be given to liquidity management, redemption arrangements, reserve concentration and the financial connections that can transmit stress across markets. Ultimately, the credibility of a stablecoin is determined not only by what backs it, but by whether its promise can be fulfilled when everyone wants their dollars back.
Q1: How long can a stablecoin remain below $1?
There is no fixed recovery period. A stablecoin may regain its peg within hours if confidence and liquidity return quickly, while more serious problems involving reserves, banking access or redemption can keep its price below $1 for much longer.
Q2: Can stablecoin holders lose money during a temporary depeg?
Yes. Someone who sells a stablecoin at $0.95 receives only 95 cents for each token, even if the stablecoin later recovers to $1. Recovery does not automatically compensate holders who sold at a discount.
Q3: How can investors identify early signs of a possible stablecoin depeg?
Warning signs include persistent trading below $1, unusually high redemption activity, declining market liquidity, delayed reserve disclosures and negative announcements involving an issuer’s banking partners or custodians.
Q4: Does a stablecoin’s market capitalization affect its depegging risk?
Market capitalization alone does not determine stability. However, a large stablecoin can have greater connections to exchanges, lending platforms and financial markets, meaning its depeg may have wider consequences. Reserve quality, liquidity and redemption capacity remain more important indicators of its ability to maintain the peg.
Sources (4)
- Federal Reserve: In the Shadow of Bank Runs (2025, December).
- IMF: From Par to Pressure (2026, January).
- IMF: Making Stablecoins Stable (2026, April).
- Federal Reserve: Primary and Secondary Markets for Stablecoins.
Muhammad Mubashir is a crypto enthusiast who has been in the Web3 space since 2019 and writing content for major industry platforms since 2024. They specialize in blockchain architecture, Layer 1/2 solutions, NFTs, DeFi, and Web3 technologies, and enjoy gaming in their free time.